The term “distressed property” gets used loosely enough in real estate that plenty of homeowners aren’t sure whether it actually applies to their own house. What is a “distressed property” in Jacksonville, exactly, matters because the label affects everything from financing options for a potential buyer to how House Buyer Joe and similar direct buyers actually approach pricing and purchasing. Understanding where your house genuinely falls on this spectrum helps you set realistic expectations rather than assuming a generic definition applies to your specific situation.
The Two Different Meanings of “Distressed”
“Distressed” actually refers to two related but distinct things: the physical condition of the property itself, and the financial or legal situation of the seller. A house can be distressed physically, needing significant repairs, structural issues, code violations, without the seller being under any particular financial pressure. Conversely, a seller can be in a distressed financial situation, facing foreclosure, an urgent relocation, an inherited property they can’t afford to maintain, while the house itself is in perfectly good condition. Most real conversations about distressed property involve some combination of both, but they’re worth separating clearly since they affect the situation differently. The Consumer Financial Protection Bureau publishes general guidance on financial hardship and housing options that’s useful context for anyone navigating the seller-distress side of this equation specifically.
Physically Distressed: What Actually Qualifies
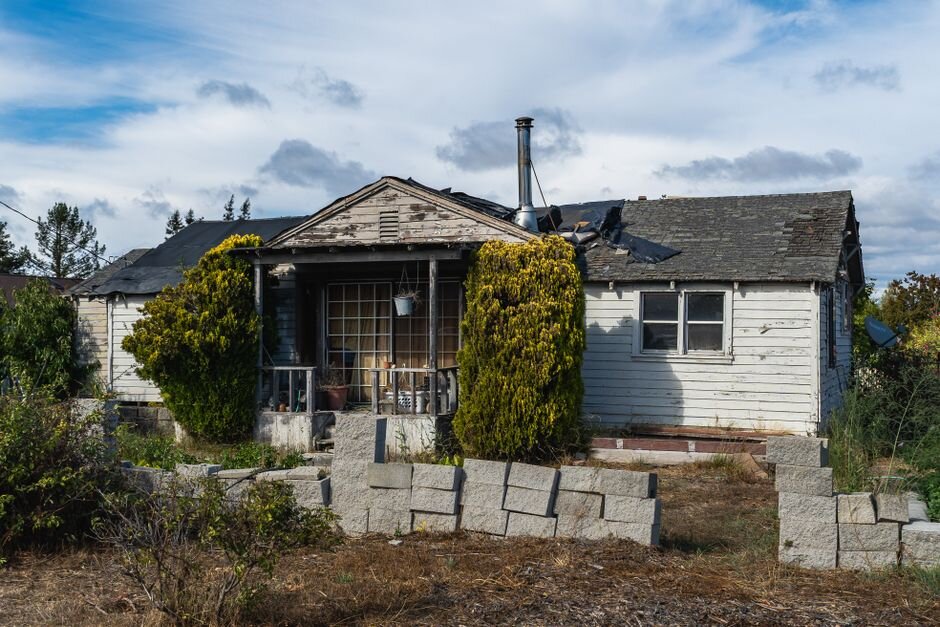
A physically distressed property typically has one or more serious issues: a failing roof, foundation problems, outdated or unsafe electrical and plumbing systems, significant water or fire damage, or code violations serious enough that the property wouldn’t pass a standard inspection. This is meaningfully different from a house that’s simply dated or cosmetically tired, outdated kitchen cabinets or old carpet don’t put a property in genuinely distressed territory the way a compromised roof structure or failing septic system does.
Code violations deserve their own mention here, since they can push an otherwise reasonably maintained house into distressed territory on paper even when the physical issues seem relatively minor. An unpermitted addition, an expired certificate of occupancy, or an open code enforcement case can all complicate a traditional sale considerably, sometimes requiring resolution before a lender will even consider financing a buyer’s purchase, regardless of how the house actually looks from the curb.
Financially Distressed: The Seller’s Situation
A financially or situationally distressed sale involves a seller facing real pressure to sell quickly, foreclosure, divorce, a job relocation with a firm start date, an inherited property with mounting tax and insurance bills, or simply a landlord who’s exhausted managing a difficult rental. In these cases, the property itself might be in fine condition, the distress is entirely about the seller’s circumstances and timeline, not the physical asset.
This distinction matters enormously for how a seller should approach the process. A physically distressed house genuinely needs a buyer comfortable taking on repairs, regardless of how much time pressure exists. A situationally distressed seller with a well-maintained house has more flexibility, a traditional listing could work if there were enough time, but a direct sale often ends up the better fit purely because of the timeline constraint, not because anything is actually wrong with the property itself.
Why Financed Buyers Avoid Both Categories
Traditional financed buyers and their lenders generally avoid physically distressed properties because most loan programs require a house to meet minimum condition standards to qualify for financing at all. Situationally distressed sales create a different problem for financed buyers, an urgent seller timeline often can’t accommodate the 30 to 45 days a typical financed closing requires, meaning even a well-qualified buyer’s timeline simply doesn’t match what the seller actually needs. The National Association of Realtors tracks broader financing and closing timeline trends nationally, useful context for understanding just how much a typical financed closing timeline can vary and why that variability creates real risk for a seller on a tight deadline.
Why This Matters for Pricing Your House Accurately
Understanding which category, or combination of categories, actually applies to your situation shapes realistic pricing expectations. A physically distressed house needs to be priced against what an investor would actually pay accounting for repair costs, not against move-in-ready comparable sales in the same neighborhood. A situationally distressed sale with a house in good condition can often still command a fair, near-market price from a direct buyer, since the urgency is about timeline, not the property’s underlying value.
How House Buyer Joe Approaches Both Categories
House Buyer Joe buys houses across the entire distressed spectrum, physically distressed properties needing significant work, situationally distressed sellers facing an urgent timeline, and combinations of both. No repairs required, no financing contingencies to derail a sale, and a closing timeline that can move as fast as the situation genuinely requires, as little as seven days in a true emergency, though that’s the floor rather than the typical timeline.
This flexibility matters because plenty of homeowners assume their situation is somehow “not distressed enough” to qualify for this kind of direct sale, or conversely assume their house is “too far gone” to interest any legitimate buyer. Neither assumption is usually accurate, and a direct conversation about your specific property and circumstances gives a far more accurate picture than guessing based on a generic definition. Sellers are sometimes surprised to learn that a house they’d written off as unsellable due to its condition is genuinely within the range of properties we buy regularly, and just as often, a seller assumes their situation isn’t urgent enough to warrant a direct sale when in fact the timeline pressure they’re under is exactly the kind of scenario this option exists for.
A Necessary Note on YMYL Situations
If your version of “distressed” involves foreclosure, bankruptcy, or other legal or financial proceedings, every situation carries its own specific facts, and general information like this isn’t a substitute for individual legal or financial advice. It’s worth a direct conversation with an attorney or CPA about your specific circumstances alongside any conversation about selling.
Why Josiah Understands Both Sides of This Spectrum
Having spent 11 years as a licensed realtor before starting House Buyer Joe, Josiah has seen both physically distressed properties and situationally distressed sellers up close, often at the same time. That experience shapes an approach built around understanding your specific situation honestly, rather than applying a one-size-fits-all label to every seller who reaches out.
Not Sure Which Category Describes Your House?
Whether your property is physically distressed, you’re facing a distressed timeline, or you’re simply unsure which label actually applies, reach out to House Buyer Joe for a straightforward, honest conversation and a no-obligation cash offer.